Skip to content


A standard homeowners policy usually covers a garage door when about 1 in 18 insured homes files a claim in a year and the damage comes from a covered peril like wind, hail, fire, vandalism, or vehicle impact. It usually does not cover wear and tear, rust, broken springs from age, mechanical failure, or deferred maintenance.
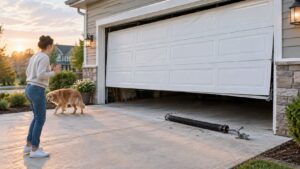
If your garage door is bent after a Cleveland windstorm or won't open the next morning, don't guess. The key question is what caused it, whether the garage is attached or detached, and whether the repair cost is higher than your deductible.
The Short Answer for Homeowners
A bent door after a Northeast Ohio storm usually points to an insurance claim, but the policy only cares about the cause. Wind, hail, fire, vandalism, or a vehicle hit can fall under a standard homeowners policy as a covered property loss. Springs that wore out, an opener that failed, rust, and neglected maintenance usually do not.
Start with cause, not appearance
A garage door can look ruined and still be covered. It can also look minor and still be a repair bill you have to pay yourself. The same damage produces different results depending on whether it came from a sudden event or from slow wear.
Adjusters and contractors ask the same first question for a reason, what happened right before the door failed? A storm, break-in, impact, or fire points toward coverage. Age, corrosion, and poor upkeep point away from it.
Practical rule: If something happened to the door, insurance may help. If the door wore out, insurance usually will not.
Attached and detached garages are not treated the same
For a standard policy, an attached garage usually falls under dwelling coverage, Coverage A. A detached garage usually falls under other structures coverage, Coverage B. That split affects the claim limit, and the deductible still applies either way.
One industry explainer notes that detached-garage coverage often defaults to 10% of dwelling coverage, so a home insured for $250,000 may have about $25,000 for detached structures, according to MoneyGeek's coverage breakdown. The size of the garage, the policy language, and the deductible decide whether the claim makes financial sense.
The clean answer is simple. Cause first. Coverage bucket second. Deductible last.
How Garage Door Coverage Works
A lot of homeowners say “my garage door is covered” when they really mean three different things. The door itself, the opener, and the garage structure are not the same object from an insurance standpoint. A broken opener motor can be a mechanical issue, while a crushed door panel can be property damage, and the garage shell may sit in a different part of the policy altogether.
For a standard homeowners policy, the coverage bucket depends on the garage's physical setup. An attached garage is generally treated as part of the home, so an adjuster usually looks to dwelling coverage, Coverage A. A detached garage usually lives under other structures coverage, Coverage B, which is often smaller than the dwelling limit and can shape how much room you have for repairs or replacement.
If you want a plain-English refresher on the structure of homeowners coverage, what homeowners insurance actually covers is a useful starting point. That matters because the policy language, not the door style, controls the claim.
| Garage Type | Typical Coverage Part | What the Homeowner Should Check |
|---|---|---|
| Attached garage | Coverage A, dwelling | Declarations page, exclusions, deductible, repair scope |
| Detached garage | Coverage B, other structures | Limit amount, whether it's near the default, deductible, endorsements |
| Garage opener or hardware | Often depends on the cause and policy wording | Whether the failure was sudden damage or mechanical wear |
The policy bucket changes the claim strategy
Here's the practical reason this split matters. An attached garage often has more room under the main dwelling limit, while a detached garage may have a tighter cap. If hail dents the detached door, the loss may be covered in principle but still run into a smaller limit than the same damage on an attached garage.
Check your declarations page first. The real answer is usually sitting in Coverage A, Coverage B, the deductible line, and any endorsement list.
Don't assume every policy is identical. Confirm the exact wording in your own policy forms, especially exclusions and any special structure limits. For a homeowner, landlord, or property manager, that one page tells you where the adjuster will look first when the door is damaged.
Covered Perils and Common Exclusions
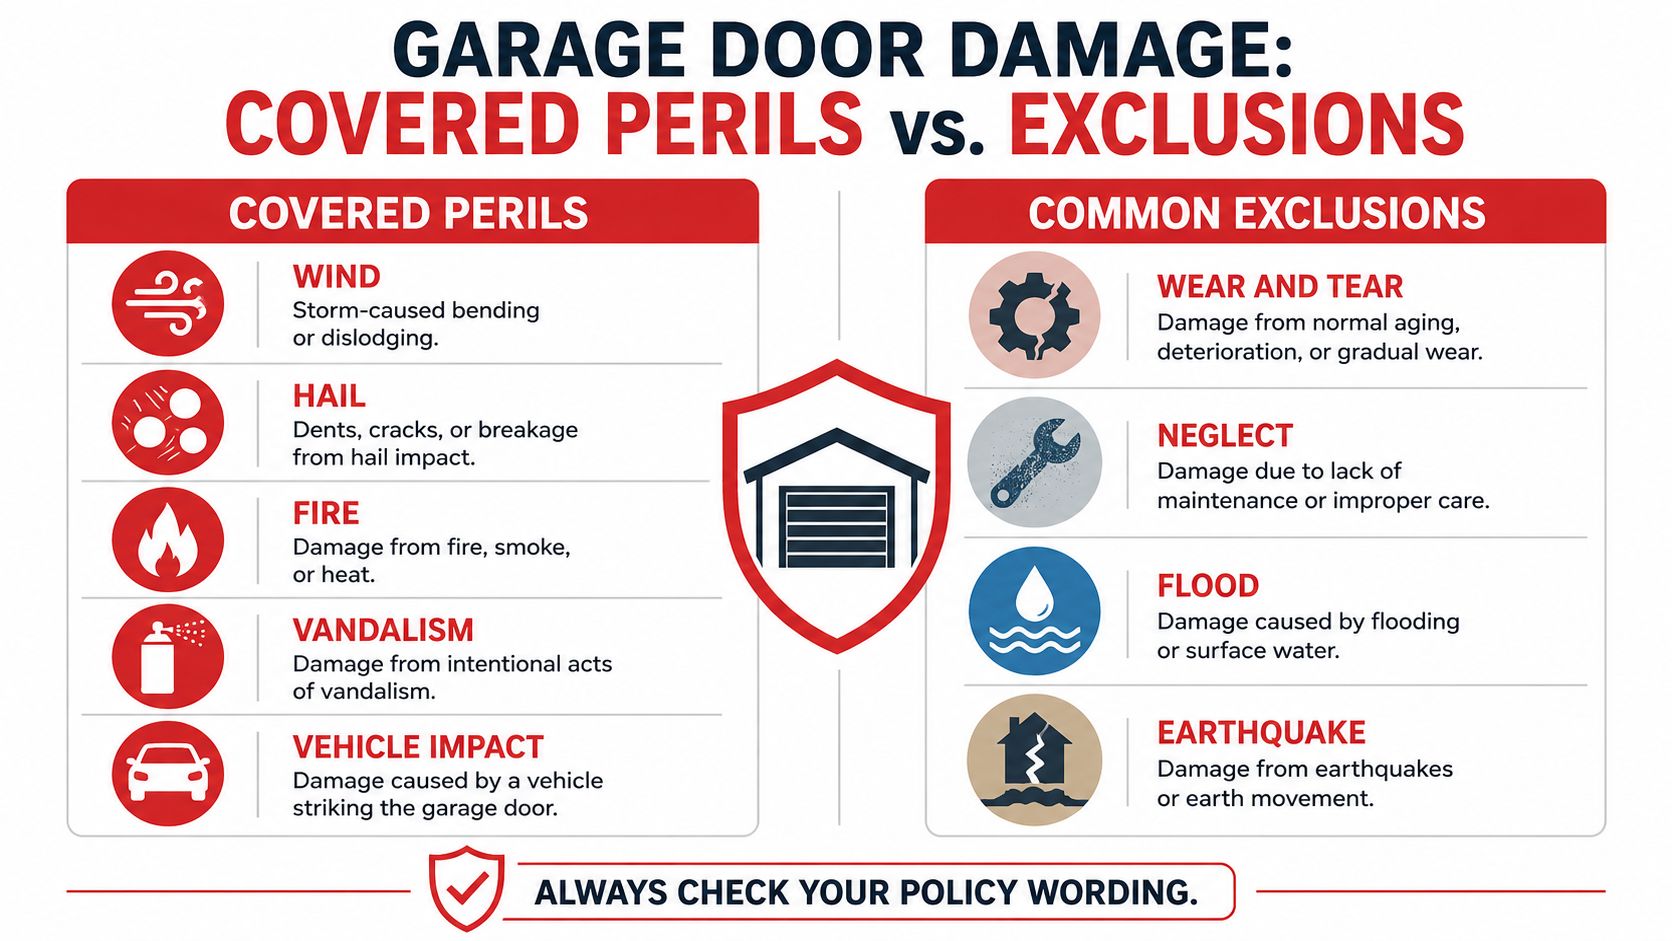
The easiest way to sort a claim is to ask whether the damage came from a covered event or from a problem the door was already developing. Insurance usually helps when the loss is sudden and external. It usually doesn't help when the door was wearing out in slow motion.
What usually points toward coverage
Covered garage-door losses often start with a visible event. Wind can buckle a panel or push a door off track. Hail can dent the face of the door. Fire can damage the door and the surrounding structure. Vandalism and vehicle impact are also common claim triggers when they're clearly documented.
The Insurance Information Institute reports about 1 in 18 insured homes has a claim each year, and about 1 in 36 has a property damage claim tied to wind or hail, according to the III homeowners and renters insurance facts. Those are exactly the kinds of events that can damage a garage door fast. The same dataset shows about 1 in 430 insured homes has a fire and lightning claim, and about 1 in 850 has a theft claim, which also lines up with the types of losses that can affect garage doors.
What usually points away from coverage
Wear and tear is the big exclusion homeowners miss. Rust, aging springs, deteriorated tracks, and an opener that finally dies after years of service are usually maintenance issues, not insurance losses. A door that looks broken isn't automatically a covered claim.
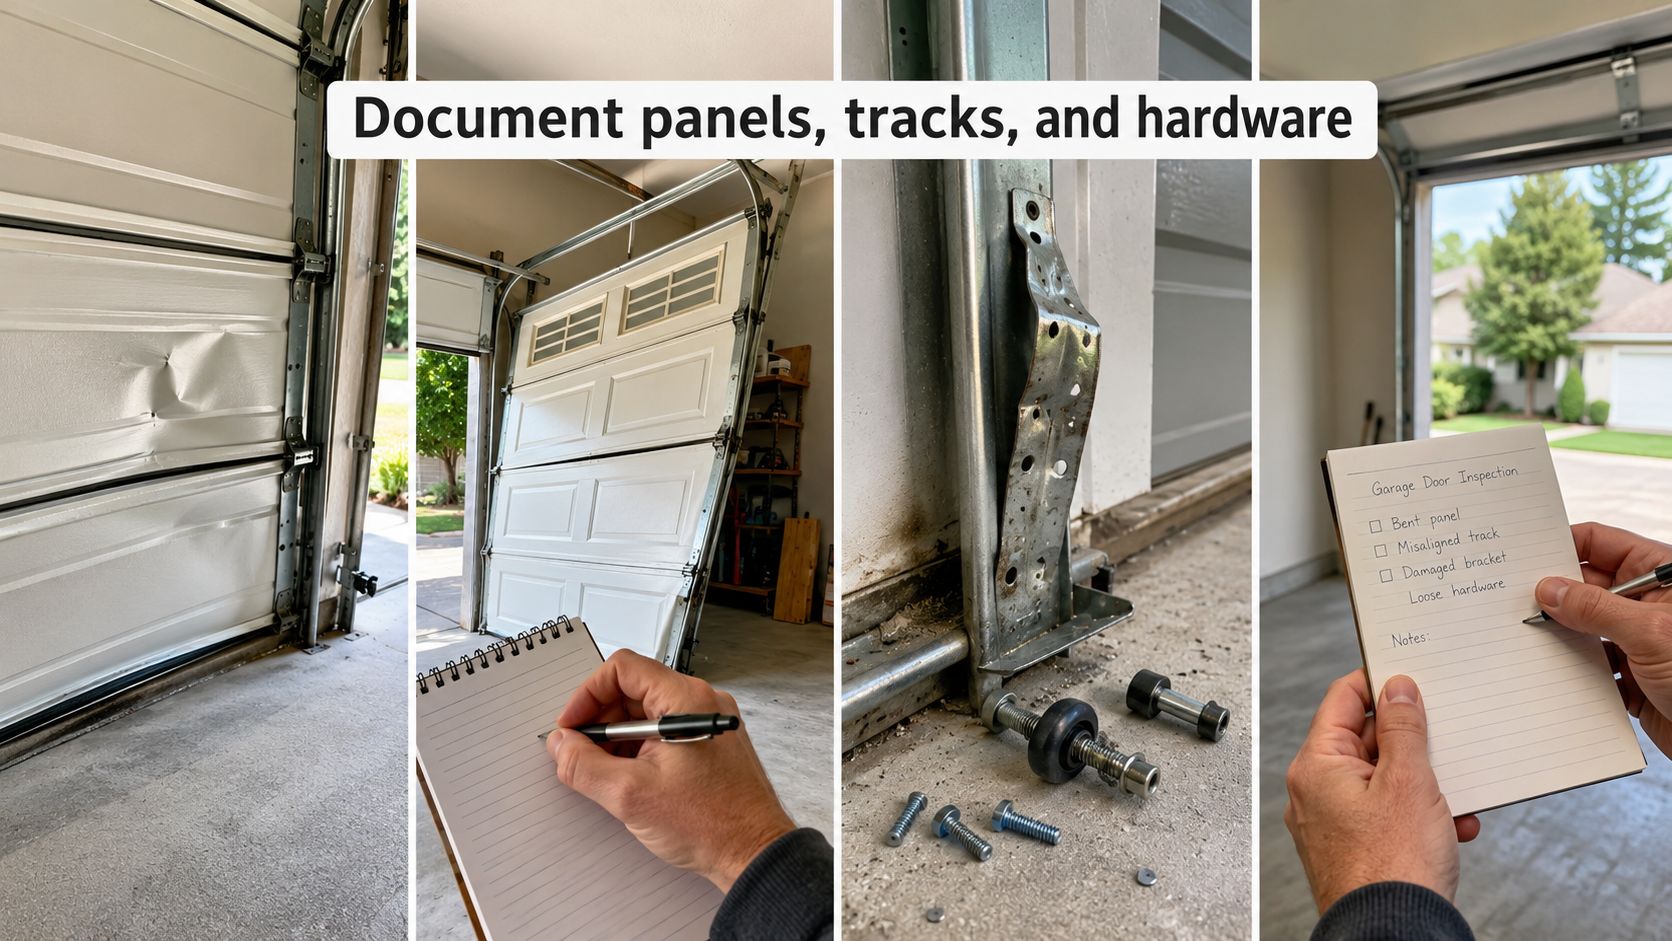
A broken spring is a good example. It can stop the door cold, but a spring failure by itself does not prove a covered event. One guide notes torsion and extension springs commonly last about 10,000 to 20,000 cycles, or roughly 7 to 12 years, which is why age-related failures are so often treated as maintenance problems rather than losses. For a broader comparison of roof and tree damage logic, explore tree damage insurance coverage shows the same cause-first principle at work.
The screening question is blunt, and it works. Was the damage sudden and external, or gradual and maintenance-related? If you can answer that cleanly, you're already halfway to knowing whether a claim makes sense.
Real Garage Door Damage Examples
A garage door claim gets easier to understand when you stop talking in policy language and start talking about what happened. The shape of the damage matters, but the sequence of events matters more. That's where homeowners usually win or lose the claim.
Wind, vandalism, wear, and impact look different on the ground
If a storm blew through Cleveland and the door is now bent, stuck, or partially dislodged, document every affected part. Get photos of the panels, tracks, rollers, cables, and brackets before anyone starts work. A contractor's field notes can also help separate storm damage from a door that was already shaky.
If someone forced entry or vandalized the door, keep the scene intact as much as safety allows. Photos matter, and so does the police report number if law enforcement was involved. The insurer doesn't need a dramatic story, it needs a clean record of what was damaged and when.
If a spring snapped after years of use, don't treat that like storm damage just because the door stopped working loudly. Age-related spring, cable, roller, and opener failures are usually maintenance claims, not insurance claims. The same goes for track deterioration or an opener that's worn out.
If a car backed into the door, that can be a covered accident when the event is clear and the damage is consistent with the impact. Still, pre-existing defects can complicate the claim, especially if the door was already off balance or had old damage that a contractor noticed during inspection.
The adjuster doesn't care how bad the door looks. The adjuster cares what caused it.
Don't let visible damage tell the whole story
A bent panel can come from wind, impact, or a door that had weak hardware and finally gave out. That's why the contractor's opinion and the timing of the event matter. One bad panel might be enough for repair, but a pre-existing alignment problem can make the insurer question the scope.
For homeowners, the best move is simple. Write down the event, photograph the condition, and save anything that helps show the door was functioning before the loss. That record is stronger than memory every single time.
Deductibles and Repair Decisions
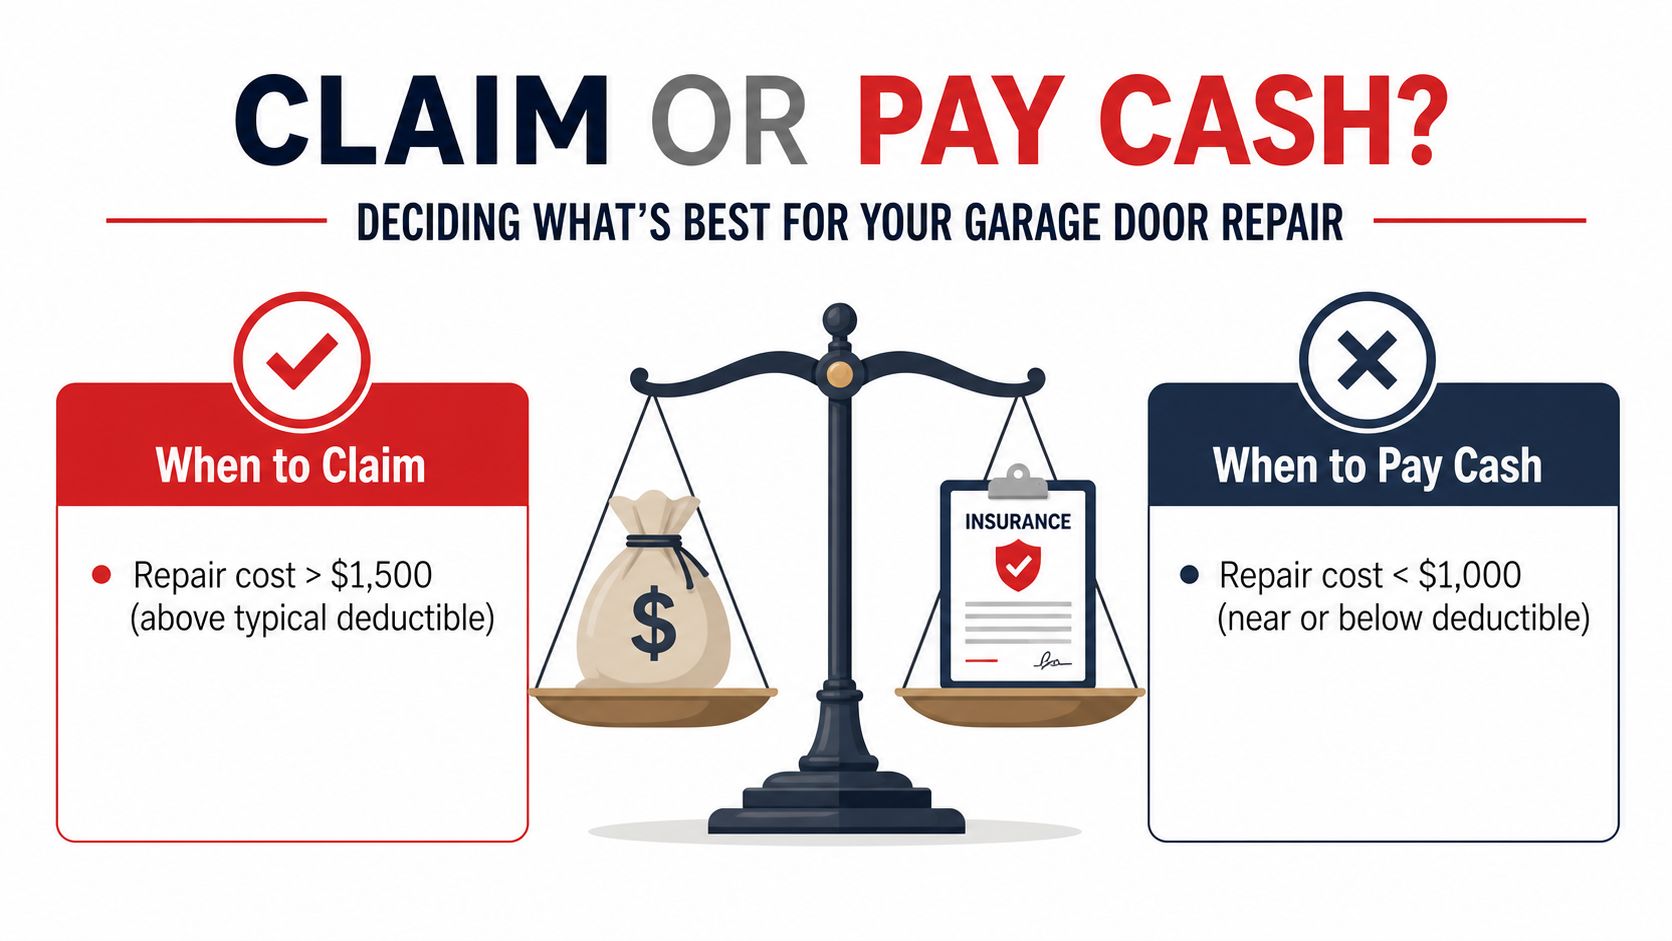
A covered loss does not automatically justify a claim. The deductible is your share of the bill, and that changes the decision fast. If the repair estimate sits near your deductible, paying cash often makes more sense than turning in a claim.
Policy guidance is plain on this point. If the repair cost is below the deductible, you usually come out ahead by paying out of pocket. That logic fits garage doors well, because a broken spring, one damaged panel, or a basic track repair can stay under the deductible even when the problem feels urgent.
Compare the estimate to the deductible first
Start with a written estimate from a garage door pro. Then compare that number to your deductible and answer one direct question, is the claim worth it?
A cited average replacement cost of $1,250 without insurance from SmartFinancial gives you a rough benchmark, but it does not set your actual price. In Northeast Ohio, the number changes with the door style, the parts required, and whether the job is a repair or a full replacement. For a local pricing frame, use garage door repair cost guidance as a starting point, then get your own estimate in writing.
Look at coverage limits and repair scope too
Detached garages can run into Coverage B limits even when the loss is covered. Attached garages usually raise a different question, whether a single-panel fix is enough or whether the whole door needs replacement to operate safely and match the existing setup. Matching materials matter, and parts availability matters too.
If the door can be repaired safely, that is usually the better move. If the structure is compromised, replacement may be the only sensible fix. The estimate should separate emergency stabilization, parts, labor, and any follow-up work so you can see what belongs in the claim and what is normal maintenance.
File a Garage Door Claim With Evidence
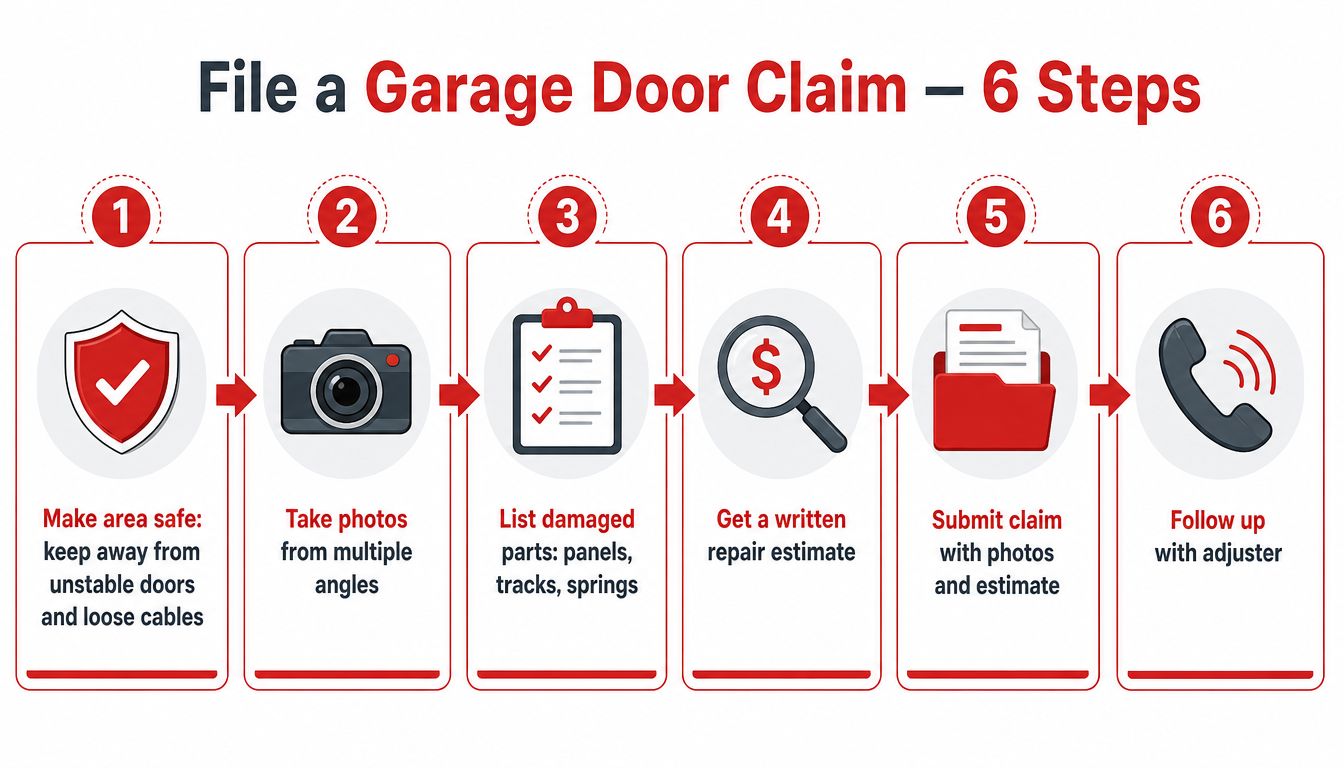
Start with safety, not paperwork. If the door is off track, hanging crooked, or loaded with tension, keep people away from it and call a qualified garage door professional to secure it. Springs and cables can be dangerous, and a bad move can turn a repair into an injury.
Then contact the insurer promptly and state the suspected cause in plain language. Don't embellish, and don't guess if you don't know. A clean statement like “the door was struck by a vehicle” or “the door was damaged during a windstorm” is better than a vague story that changes later.
Build the claim file before parts disappear
Use dated wide shots and close-ups. Save photos of the door face, tracks, hardware, frame, opener, and any debris or impact marks. Keep receipts, maintenance records, the contractor's written findings, and the estimate together in one file.
If vandalism is involved, keep the police report number with the claim documents. If the adjuster asks for proof of prior condition, your maintenance records can help show that the door was being cared for before the event. That matters because insurers are looking for cause, timing, and condition, not just damage.
free garage door repair estimates are useful here because a written scope makes the claim easier to review. Don't throw damaged parts away unless safety requires it or the insurer tells you to. If a broken spring or bent track is still available for inspection, leave it alone until the claim is documented.
Keep emergency safety work separate from claim evidence. The person securing the door shouldn't blur the facts about what broke and why.
The goal is simple. Give the insurer a clear record, give the contractor a safe work area, and give yourself the best shot at a fair decision.
Northeast Ohio Risks and Contractor Help
Cleveland and the surrounding suburbs get the kind of weather that exposes weak garage doors fast. Wind, hail, snow, ice, and fast temperature swings can all make an already tired door fail at the worst possible time. If the door shifts off track after a storm, it's not just an insurance issue. It's a safety issue first.
The right contractor response is to make the door safe and operable, not to argue coverage. Emergency stabilization, spring work, cable replacement, off-track corrections, opener repairs, and full installations are different jobs, and the estimate should separate them clearly. That separation helps homeowners, landlords, and adjusters understand what was storm-related and what was mechanical repair.
Danny's Garage Door Repair serves Cleveland and nearby communities with emergency garage door help, scheduled repair, spring and cable replacement, off-track corrections, opener work, and installations, with offices in Pepper Pike and Brunswick and technicians available 24/7. If you need local help, garage door repair in Cleveland, OH is the practical place to start.
Warranty coverage is not a substitute for homeowners insurance. A warranty may help with certain parts, while insurance responds to sudden external damage. Keep those two lanes separate so you don't waste time calling the wrong party first.
A Simple Coverage Decision Checklist
Start here when the door is damaged. Identify whether the garage is attached or detached, write down the suspected event, and check for immediate hazards like broken springs, hanging cables, or a door that's off track. Then compare the written estimate to your deductible and look at Coverage A or Coverage B in your declarations page.
If the cause looks like wind, hail, fire, vandalism, or vehicle impact, call the insurer and document the loss. If the cause looks like rust, age, or mechanical failure, plan on a repair bill instead. The visible damage doesn't settle the claim, the cause and policy language do.
Stop using a garage door that has broken springs, loose cables, an off-track panel, or an opener that moves unpredictably. Get it inspected by a professional before anyone tries to force it closed or open.
If your garage door was damaged and you want a straight answer fast, Danny's Garage Door Repair can inspect the problem, secure the door, and separate emergency work from the repair scope. Visit Danny's Garage Door Repair to request help from a Cleveland-area team that handles repairs, replacements, and storm-related garage door problems every day.